Credit Score 750+: How Working Professionals Can Build and Maintain Excellent Credit
India-specific guide: This article covers TransUnion CIBIL scores in India (300–900), not US FICO scores. The same number can have a different meaning in different countries. For US credit-scoring information, refer to the Consumer Financial Protection Bureau.
Your credit score is one of the most financially powerful numbers in your life. A strong CIBIL score can help your eligibility for some lending products, but lenders evaluate income, repayment history, debt obligations and other factors too. No particular score automatically guarantees approval or the lowest interest rate. Yet most professionals have no strategy for building or protecting their score. Here is a complete guide.
What Is a Credit Score and Why Does 750 Plus Matter?
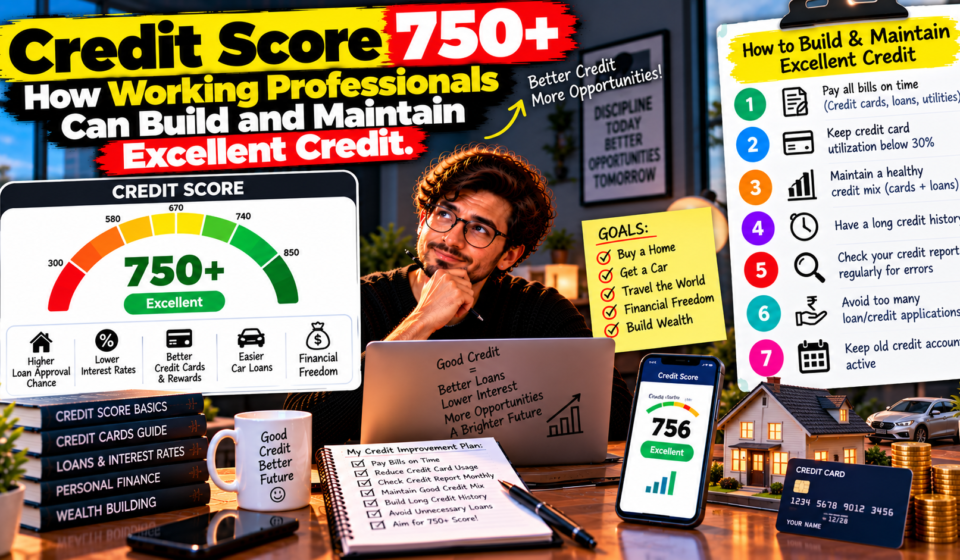
A credit score, called the CIBIL score in India, is a 3-digit number ranging from 300 to 900 that represents your creditworthiness. Scores of 750 or higher are often considered strong by Indian lenders, but approval, pricing, and eligibility depend on the lender, credit history, income and other underwriting factors; no score guarantees the best rate. The difference between a 650 and 780 CIBIL score on a Rs 50 lakh home loan can mean paying 0.5 to 1 percent higher interest, which translates to Rs 5 to 10 lakh extra over 20 years.
The 5 Factors That Determine Your Credit Score
Payment history, credit utilisation, length and depth of credit history, credit mix and recent inquiries can influence credit scores. However, the familiar 35/30/15/10/10 breakdown is associated with some US FICO score explanations; it should not be presented as TransUnion CIBIL’s published weighting formula. CIBIL’s proprietary model and lender decisions differ. For Indian consumers, start with TransUnion CIBIL’s official resources.
Step 1: Get Your Free Credit Report and Check for Errors
You are entitled to one free CIBIL report per year. Get it at CIBIL.com and check it carefully. Errors — wrong personal details, accounts that are not yours, loans shown as active when closed — are more common than you think and can be damaging. Dispute any errors immediately through CIBIL’s online portal. Corrections typically take 30 to 45 days.
Step 2: Never Miss a Payment
A late payment can negatively affect your credit history and score. Its impact varies and should not be described as a fixed 50–100-point drop or an identical reporting period for every case. Set up auto-payment for at least the minimum due on all credit cards and EMI auto-debit for all loans. Even if your bank account runs low, prioritize these payments above everything else. Missing an EMI is one of the most expensive financial mistakes you can make.
Step 3: Manage Your Credit Utilization Wisely
If your total credit card limit is Rs 1,00,000, keeping your monthly spending below Rs 30,000 across all cards maintains healthy utilization. If you regularly spend more, either request a credit limit increase without increasing spending or get an additional card to spread the utilization. High utilization signals financial stress to lenders, even if you pay in full every month.
Step 4: Build Credit History Early
If you are early in your career with no credit history, start with a secured credit card against a fixed deposit. Use it for small purchases and pay the full amount every month. Do not cancel old credit cards — their age contributes positively to your score. An account that is 8 years old is an asset, even if you rarely use it.
Step 5: Be Strategic About Loan Applications
Every time a lender does a hard inquiry on your credit report, your score drops slightly. If you are planning to apply for a home loan or car loan in the next 6 months, avoid applying for new credit cards, personal loans, or any other credit product. Multiple inquiries in a short period make you look credit-hungry to lenders.
Building a 750 plus credit score is not complicated, but it requires consistency over time. Pay on time, keep utilization low, maintain old accounts, and check your report annually. Do this for 2 to 3 years and your credit score will save you lakhs of rupees in interest over your lifetime.