Rent vs Buy in the USA: Calculate Your Real Housing Break-Even Point
US home-buying decision guide, November 2026. All numbers in examples are fictional and for calculation only, not current market quotes or investment advice.
“Renting is throwing money away” and “buying always builds wealth” are both too simple to guide a major housing decision. Renting provides housing and often flexibility without putting the renter in charge of a building’s large repairs. Owning may build equity, but it also brings taxes, insurance, maintenance, closing costs, financing interest and the possibility that prices do not rise as expected. Comparing a rent payment with only the principal-and-interest portion of a mortgage is not an apples-to-apples calculation.
The question most US households should answer is: over the period we realistically expect to live in this location, which choice better fits our cash flow, risk tolerance and life plans? This guide gives a framework for comparing the options without pretending that one simple “break-even year” works for every household.
1. Start with your realistic time horizon
A home purchase usually has meaningful transaction costs. The buyer may pay loan origination charges, title and settlement fees, appraisal costs, prepaids and other closing expenses. Selling later may require additional transaction costs and possibly concessions or repairs. If you expect to move in eighteen months, those expenses are spread across a short period, making ownership economically different from staying seven or ten years.
Ask whether a career move, relationship change, childcare need or family obligation may prompt relocation. A long-term plan can change unexpectedly, but honest planning matters. Do not justify a purchase solely by assuming you will remain in one neighborhood forever. Home ownership can reduce flexibility even when the monthly cash payment initially looks attractive.
The CFPB Buying a House resources explain mortgage costs and transaction documents. Use your own Loan Estimate and expected sale costs, not generic percentages from a national blog, to model this part accurately.
2. Calculate the full monthly cost of ownership
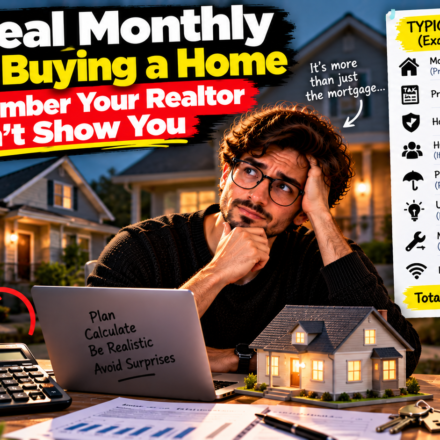
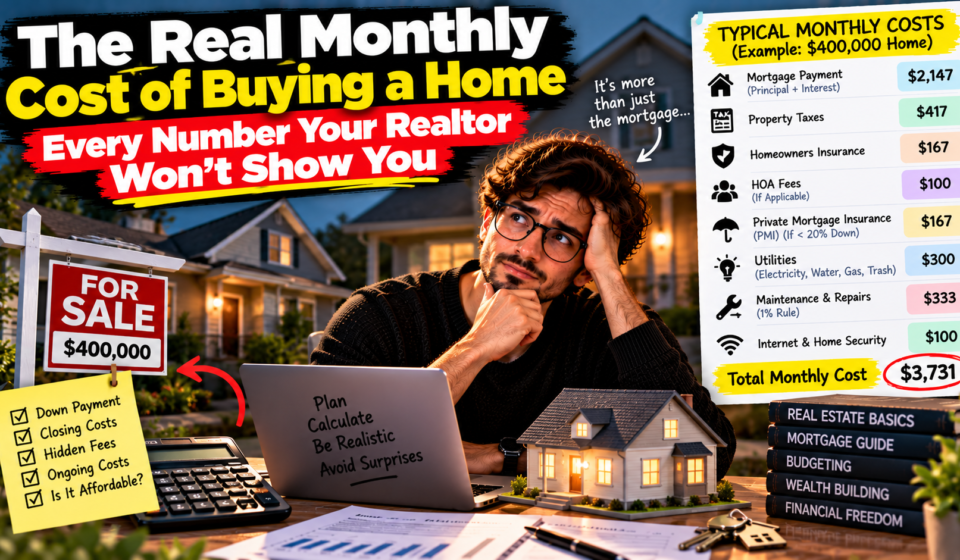
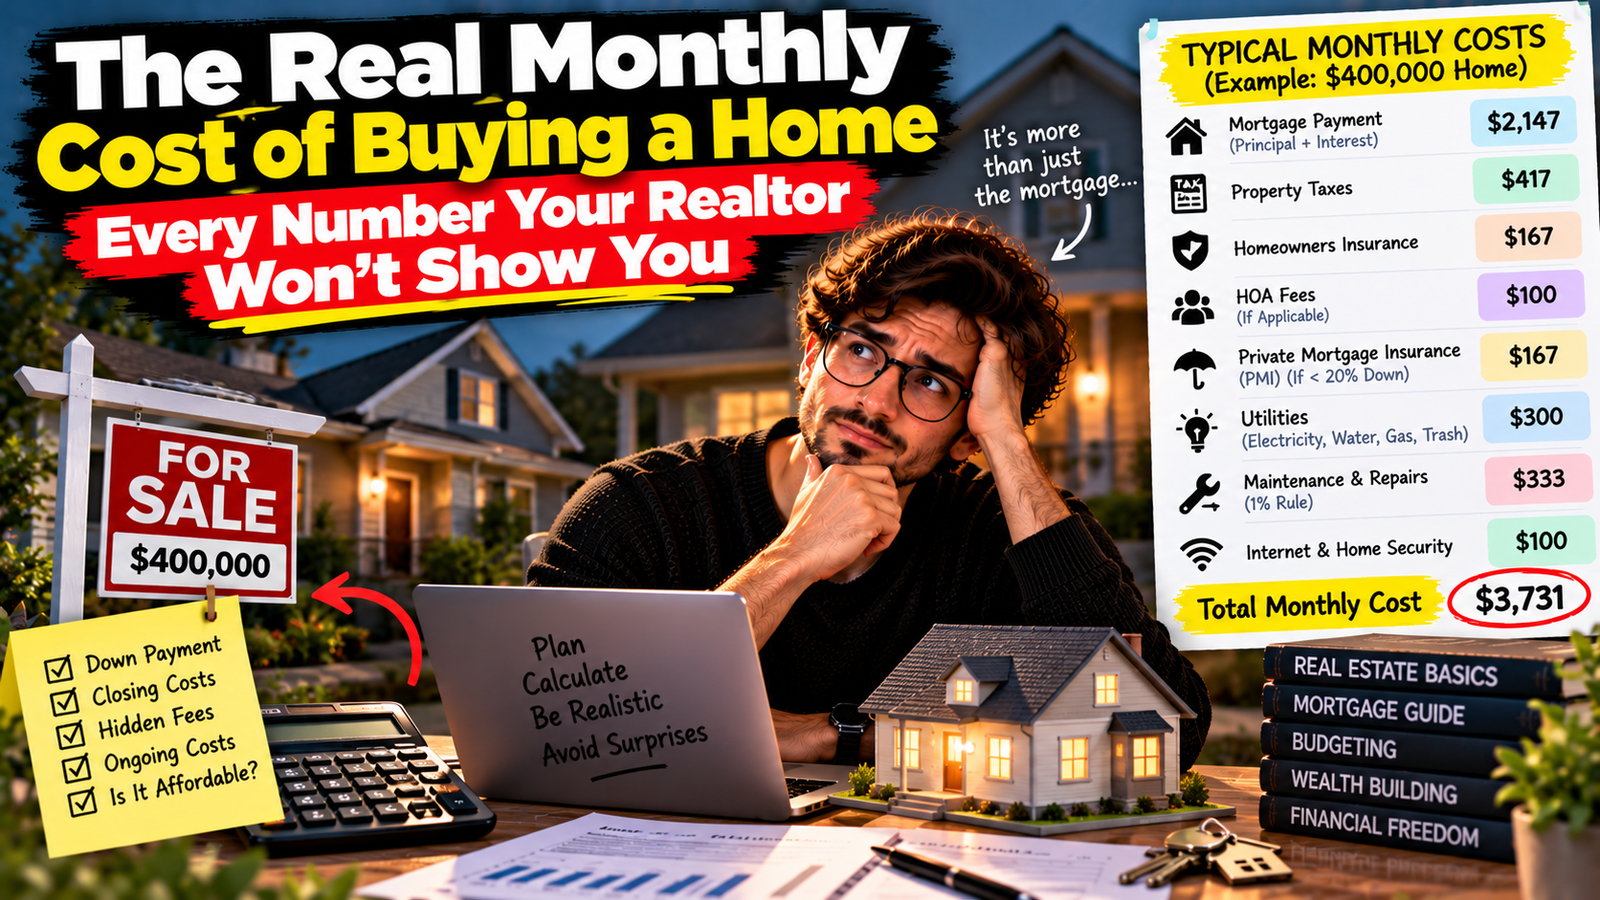
Mortgage principal and interest are only the start. Add property taxes, homeowners insurance, any mortgage insurance, HOA or condo dues, repairs, maintenance and applicable utilities that would not be paid in a rental. Then consider the cash tied up in the down payment and purchase expenses. The homeowner’s total monthly cash outflow can differ markedly from the payment advertised in a property listing.
For an illustrative property priced at $360,000, assume a $72,000 down payment and $288,000 mortgage at a hypothetical fixed rate of 6.5% over thirty years. Principal and interest are approximately $1,820 per month, depending on actual calculation and rounding. Now add $350 in monthly property taxes, $150 in insurance, $100 in HOA dues and a $250 maintenance reserve. The total planning amount becomes about $2,670 per month before other possible costs.
That $250 maintenance reserve is not an invoice paid every month; it represents money set aside for irregular repairs. Real repair costs are lumpy. A heating system may work for years and then require a major replacement during one season. A buyer who compares rent with only $1,820 in principal and interest understates the ownership cash commitment.
3. Count the true renter costs too
Renters have costs beyond base rent. Consider renter’s insurance, fees that are disclosed in the lease, parking, utilities, deposits and likely rent increases. Some renters must pay a substantial moving cost or incur a lease-break fee. A landlord’s responsibility for many building repairs is a service embedded in the rental arrangement rather than “free money.”
Imagine the comparable rental costs $2,150 per month, plus $20 for renter’s insurance and $60 of parking that would be included for the owned home. That produces $2,230 monthly cash outflow, about $440 below the hypothetical owner cash requirement of $2,670. This difference is not automatically the renter’s investment return: the comparison also needs principal repayment, appreciation, alternative investment choices and transaction costs.
Read the actual lease to understand which repairs and utilities are the renter’s responsibility. Likewise, an HOA agreement can shift some maintenance to an association but create monthly dues and special assessment exposure. Never compare two homes as if their utilities, amenities and location were identical unless they really are comparable.
4. Separate mortgage principal from true expense
Part of each amortizing mortgage payment repays loan principal and builds equity, while interest compensates the lender. Principal is a form of balance-sheet transfer from cash to home equity, not the same economic expense as interest. That distinction makes a pure cash-flow comparison incomplete. Yet treating principal as guaranteed savings is also misleading because home value may decline and selling is costly.
For the illustrative $288,000 mortgage at 6.5% over thirty years, the first payment includes a much larger interest portion than principal portion. Over time, the principal share generally increases. Use an amortization schedule for your actual rate, term and extra payments rather than assuming equal wealth-building every month.
Owning also has opportunity costs. A $72,000 down payment and closing costs cannot simultaneously remain invested in a diversified portfolio or in emergency savings. The alternative return is uncertain; any assumed investment growth should be shown as a scenario, not as a promise. The buyer may benefit from home appreciation, but they can also lose equity in a downturn.
5. Make the break-even model transparent
A useful decision model tracks two columns across each year. For renting: rent, renter fees, moving costs if applicable, and the future value of any money not used for buying. For owning: purchase cash outlay, mortgage payments split between principal and interest, taxes, insurance, maintenance, fees, debt balance and estimated net sale proceeds after selling costs. Use the same time horizon in both columns.
Start with a base case in which the property value stays flat, a modest appreciation case and a decline case. Do the same with rent growth and maintenance costs. A strong model should not require home prices to rise rapidly for the purchase to remain financially survivable. Financial safety matters even if the eventual modeled return is positive.
The “break-even” year is the point at which modeled cumulative economic outcomes align under your assumptions. It changes if the mortgage rate, sale costs, investment return, rent inflation or moving date changes. There is no federally certified universal break-even number. A calculator can organize inputs but cannot predict appreciation or repair surprises.
6. A worked five-year scenario
Suppose the hypothetical buyer spends $72,000 down and $10,000 on upfront closing-related costs, then pays approximately $2,670 monthly including a maintenance reserve. A comparable renter spends $2,230 monthly and retains the money that the buyer committed up front. Over five years, the owner has paid mortgage interest, principal and carrying costs; the renter has paid rent and may have invested the unused difference. On sale, the owner receives the market value minus remaining mortgage debt and selling expenses.
What if the home appreciates by 3% annually? The estimated gross value after five years would exceed the original price. But the owner should subtract selling costs, any outstanding debt and major repairs before comparing with the renter’s outcome. What if the home price falls 5% instead? The buyer may have much less net equity than expected. With a short ownership period, even moderate transaction costs can dominate the result.
This paragraph deliberately does not proclaim a winner: the actual outcome depends on several unknown assumptions. Build an editable spreadsheet that makes each variable explicit. If the result changes from “buy” to “rent” when appreciation shifts by only one percentage point, you should treat the conclusion as sensitive, not decisive.
7. Affordability matters separately from investment return
A house can look attractive in a long-term financial model and still be unaffordable month to month. Lenders use underwriting criteria to decide what they may finance, but approval does not mean the payment fits every household’s comfort level. Include existing debt, variable income, childcare, healthcare, retirement saving and a cash reserve in your own affordability review.
When buying with a low down payment, mortgage insurance may apply depending on the loan program and terms. This adds to total housing cost. Also consider property tax reassessments, insurance premium increases and HOA special assessments. A fixed interest rate does not freeze those components. Our US mortgage payment calculator helps estimate components, but it does not substitute for lender disclosures.
A renter can face nonrenewal, moving expenses and future rent hikes. Consider housing stability as a legitimate benefit rather than pretending all decisions can be reduced to a spreadsheet. Homeownership can provide control over renovations and longer-term continuity, while renting can preserve mobility and reduce exposure to catastrophic building repairs.
8. Include the location and building type
Two houses with the same price may have different taxes, insurance, commuting costs and climate risks. A property in a high-risk flood or storm area may require coverage or repairs that a national median estimate misses. Local utility bills, energy efficiency, access to schools and transit may change both budget and daily experience. Property value trends can also be highly localized.
Condominiums add another layer: reserve adequacy, HOA dues, rules, master insurance coverage and possible special assessments. A modest mortgage payment paired with an underfunded association can be misleading. Request the relevant association records through your transaction professionals and examine what the buyer would actually be responsible for.
Older properties may need major replacements shortly after purchase even if they appear attractive in photos. Seek a proper inspection and specialized opinions when needed. Read our inspection versus appraisal guide to understand why a favorable lender valuation does not guarantee building condition.
9. Look at taxes carefully, without assuming a benefit
Some homeowners may qualify for deductions associated with eligible mortgage interest or property taxes, subject to current federal rules, limits and filing choices. But a deduction is not the same as a dollar-for-dollar tax credit, and many households do not gain an incremental federal deduction because they do not itemize. State tax rules may differ.
Do not use an online calculator’s “tax benefit” estimate unless it reflects the correct tax year and your actual situation. The IRS home mortgage interest deduction publication provides official guidance. A tax professional can help if your financing, household or property use creates complexity. An investment thesis based on automatic tax savings is fragile.
10. Practical decision checklist
Before committing, write down your expected stay, realistic all-in monthly payment, down payment, closing costs, likely sale costs, cash reserve after closing, maintenance capacity and major life uncertainties. Compare at least three appreciation scenarios and two rent-growth scenarios. Ask whether the decision remains acceptable if you need to move sooner or pay for a substantial repair.
Get a written Loan Estimate from relevant lenders when appropriate and examine the Annual Percentage Rate and total closing costs, not only the headline interest rate. A slightly different rate may come with points or fees that change the economics. Never assume a teaser advertisement provides the full financing terms that will be available to you.
Then ask a nonfinancial question: would this home still be a good place to live if its market value stayed flat for five years? If the answer is no, you may be making a speculative bet rather than a housing decision.
Frequently asked questions
Is renting always cheaper than buying?
No. Costs vary with location, financing, expected stay and personal needs. Compare comparable properties using full costs and risks.
How many years do I need to stay to break even?
There is no single threshold. Transaction costs, appreciation, rent changes, investment assumptions and maintenance determine the outcome.
Does paying principal make buying free?
No. Principal creates equity but also reduces liquidity, while interest, taxes, insurance and maintenance are real costs. Equity value depends on future market prices and selling costs.
Can a mortgage payment stay fixed?
Principal and interest may be fixed for a fixed-rate loan, but taxes, insurance and other ownership charges can change.
Should I use every dollar of savings for a down payment?
That can leave you unable to handle emergencies or repairs. Consider liquidity and total closing requirements rather than maximizing the down payment in isolation.
Official sources and related reading
Consult CFPB homebuying resources, IRS Publication 936 and lender-specific disclosures. Related DevVirat articles: the real monthly cost of homeownership, inspection vs appraisal and budgeting irregular income.
Editorial note: All example figures are hypothetical and not tied to a real property or mortgage offer.