How I Saved My First $1,000 in 90 Days (Without a Side Hustle or a Pay Raise)
Nobody told me saving money would feel this uncomfortable at first.
I’d read the articles. “Cut your morning coffee.” “Stop eating out.” “Track every expense.”
Great advice. Completely useless in practice because I’d try it for 10 days, feel miserable, and go back to my old habits.
Then I found an approach that actually worked — not because it was clever, but because it was honest about how people actually behave with money.
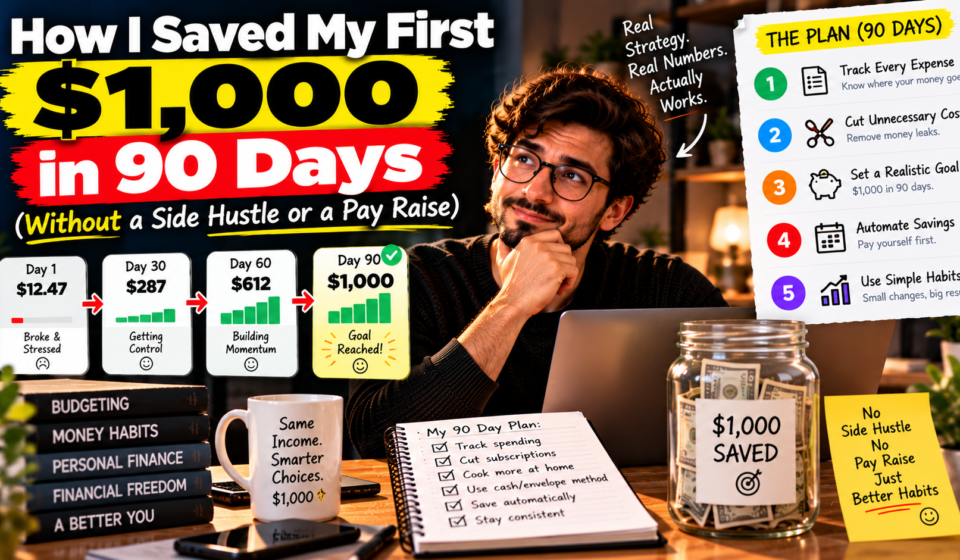
Here’s exactly what I did to save my first $1,000 in 90 days. No side hustle. No raise. Just a real system that didn’t require me to hate my life.
Why $1,000 Is the Most Important Savings Goal You’ll Ever Hit
Before the method, let me tell you why $1,000 specifically matters.
Financial experts call it an “emergency buffer.” I call it the difference between a stressful life and a manageable one.
Without $1,000 saved, a single unexpected expense — a car repair, a medical bill, a broken appliance — forces you into debt. You put it on a credit card at 20%+ interest, or you borrow from someone, and suddenly one $600 problem costs you $800 over time.
With $1,000 saved, that same situation is an inconvenience, not a crisis.
It also does something psychological: once you’ve saved $1,000, you know you can do it. Saving $5,000 feels possible. Then $10,000. The first $1,000 is always the hardest and the most important.
H2: Week 1 The Audit That Changes Everything
Here’s what most people skip: actually looking at where their money goes.
Not estimating. Not guessing. Looking at real transactions.
Open your bank statements or payment app history for the last 30 days. Write every expense into three categories:
Fixed (same every month): Rent, car payment, insurance, subscriptions, phone bill.
Variable needs (changes but necessary): Groceries, gas, utilities.
Variable wants (optional): Restaurants, entertainment, shopping, apps.
Now add up each category. Most people I’ve talked to find two things:
First, their “wants” spending is 30-50% higher than they thought. Not because they’re irresponsible — because small purchases are invisible. A $6 coffee feels like nothing in the moment. Multiply it by 20 and it’s $120 a month.
Second, they have at least 2-4 paid subscriptions they forgot about. One older subscription-spending study reported an average monthly amount of $273, but this should not be treated as a current figure or as the amount you personally spend. Review your own statements instead.
The audit alone typically reveals $100-$300/month in spending that can be redirected to savings without affecting quality of life.
The One Rule That Saved Me More Than Anything Else
Pay yourself first.
I know it sounds like a cliché from every finance book ever written. Stick with me.
The psychology behind it is real: if you wait to save “what’s left at the end of the month,” there will never be anything left. Your brain treats available money as spendable money. Period.
The solution is automatic transfers. The day your paycheck hits, an automatic transfer moves a fixed amount to a separate savings account before you ever see it or think about spending it.
Start with 10% of your take-home pay. If you bring home $3,000/month, that’s $300 automatically saved. In 90 days: $900 just from this one change.
Two important details: Use a separate bank than your checking account (the inconvenience of logging into a different account is intentional it creates friction before you spend savings). And turn off the debit card on that account.
Out of sight, genuinely becomes out of mind.
Finding Extra Money Without Making More Money
The audit showed you where money is leaking. Now let’s plug the three biggest leaks most people have.
1. Subscriptions You’ve Forgotten
Go through your bank statement and highlight every recurring charge. For each one, ask honestly: did I actively use this in the last 30 days?
If no → cancel it today. Not “I’ll cancel it later.” Today. Companies rely on the fact that cancellation feels like a hassle. It takes 3-5 minutes per service.
Commonly forgotten: fitness apps, meditation apps, cloud storage upgrades, unused streaming services, free trials that auto-converted, domain registrations, software tools.
Even cancelling 3 subscriptions at an average of $15/each frees up $45/month — $135 over 90 days.
2. The Delivery Premium
Food delivery is expensive not because the food costs more, but because the fees are hidden. Delivery fees, service fees, surge pricing, and tips can add 30-40% to your food cost without you realizing it.
This doesn’t mean never order delivery. It means making it a deliberate choice instead of a default.
One practical change: cook at home (or pick up) 3 more times per week than you currently do. For most people, this saves $80-$150/month.
3. The 24-Hour Rule for Impulse Buys
Any purchase over $30 that you didn’t plan in advance — wait 24 hours before buying it.
That’s the whole rule.
Waiting 24 hours can help reduce impulse spending, although there is no reliable universal percentage of purchases that people avoid. Either you forget about it, or the urgency disappears. The ones you still want after a day were probably worth buying anyway.
The 90-Day Breakdown
Here’s exactly how the math works if you follow this system:
Month 1:
– Auto-save 10% of income: +$300 (example)
– Cancelled forgotten subscriptions: +$45
– Reduced delivery spending: +$100
– 24-hour rule savings: +$60
Monthly savings: ~$505
Month 2:
– Continue all habits: +$505
– Sell 3-5 unused items (clothes, electronics, books): +$150-300
Running total: ~$1,010-$1,310
Month 3:
– All habits continuing: +$505
– Look for one freelance or one-time income source: +$100-300
– 90-day total: $1,500-2,000+
You’ll likely hit $1,000 somewhere in month 2. The goal is achievable — and the habits you build getting there will compound for years.
The Mistakes That Derail Most People
Setting a budget that’s too strict. If your plan requires never eating out, never buying anything fun, and being miserable — you’ll quit in 2 weeks. Build in a small discretionary budget ($50-100/month) for guilt-free spending. Restriction that’s too tight always backfires.
Keeping savings in your checking account. This is the most common mistake. Savings in the same account as spending gets spent. Non-negotiable: separate account.
Treating it as a one-time effort. The 30-day audit isn’t a one-time thing. Quick 10-minute reviews every month keep spending from creeping back up.
Comparing your progress to others. Someone else’s savings rate depends on their income, location, expenses, and circumstances. Your only comparison is your previous month.
What to Do With $1,000 Once You Have It
Keep it liquid. This is an emergency fund, not an investment. High-yield savings account, money market fund, or short-term CD — something that earns a little interest but is accessible within 1-3 days.
Don’t invest it in the stock market until you have 3 months of expenses saved. The purpose of this money is stability, not growth. Investing an emergency fund defeats the purpose markets go down, and you might need the money when the value is 20% lower.
Once you hit 3 months of expenses saved, then shift to investing. But that’s the next goal. For now, celebrate the $1,000.
Frequently Asked Questions
Q: What if I genuinely have no money left after essential expenses?
A: Start with the audit first most people find more room than they expect. Then focus on the income side: even $100-200/month of additional income from selling unused items or one small freelance project changes the math significantly.
Q: What’s the best savings account for this?
A: Compare the current APY, fees, access terms and insurance status of high-yield savings accounts. Rates change and are not guaranteed. Check FDIC deposit-insurance guidance to understand which US deposit accounts are protected and the applicable limits.
Q: Should I save or pay off debt first?
A: Save the $1,000 emergency fund first, then aggressively pay high-interest debt. The emergency fund prevents new debt from forming while you pay off old debt. It’s not either/or it’s sequence.
Q: I keep failing at saving. How is this different?
A: The auto-transfer system removes willpower from the equation. You don’t decide to save — it happens automatically. Most saving failures come from relying on willpower rather than systems. Remove the decision and you remove the failure point.